Bangladesh Rehabilitation + Physiotherapy Products, CSSD + Healthcare Waste Management Products, and FH Plastics Industry Limited

Bangladesh in January 2026 is sitting on a very simple truth: we’re treating more patients, doing more procedures, and living longer — so we need more rehab, better sterilization, and stricter waste discipline. If any one of these three breaks, hospital performance (and reputation) breaks with it.
This blog covers two product ecosystems that quietly decide whether healthcare runs smoothly or falls apart:
- Rehabilitation & physiotherapy products (devices + consumables + homecare aids)
- CSSD (sterilization) + healthcare waste management products (infection prevention + safe disposal)
I’ll give you market sizing logic, demand drivers, channel realities, challenges, and a Bangladesh case study for each side using credible sources.
1) January 2026 snapshot: What’s pushing demand in Bangladesh?
The demand drivers are not “trendy”—they’re inevitable.
- Non-communicable diseases (NCDs) are rising, and they don’t heal with dua + antibiotics. Long-term management needs rehab pathways and homecare support.
- Trauma + road injuries + workplace injuries keep climbing (Bangladesh reality: fast urban growth + safety gaps = steady rehab load).
- Post-surgery recovery is expanding with more procedures in private facilities and medical colleges.
- Patient expectations are changing: people want mobility, function, pain control, and independence — not just survival.
Now let’s talk products and money.
2) Market size and revenue: How big is this in January 2026?
Bangladesh doesn’t publish one neat number titled “Rehab & CSSD Products Market.” So we have to do what serious planners do: anchor to the best official investment market number, then segment logically.
The strongest anchor: Bangladesh medical equipment/device market
The investment authority source puts Bangladesh’s medical equipment market at ~USD 820 million by 2025 (with fast growth).
That total includes everything from imaging to disposables—so rehab + CSSD are sub-markets inside it.
A practical segmentation for January 2026 (ranges, not fantasy-precision)
A) Rehabilitation & physiotherapy products (devices + aids)
Estimated share of the overall medical equipment market: ~8%–12%
Why is this range reasonable?
- Rehab products are broad (electrotherapy, ultrasound therapy, traction, exercise/ mobility aids, orthopedic supports, homecare devices).
- Demand is expanding but still constrained by workforce availability and insurance/financing gaps. (Bangladesh rehab services remain under-integrated; many payments are out-of-pocket.)
Estimated market size (Jan 2026 run-rate): ~USD 70M–110M/year equivalent
(That’s 8%–12% of ~USD 820M, used as a planning baseline.)
B) CSSD + infection control sterilization products (equipment + consumables)
Estimated share: ~6%–10% of medical equipment market
Because sterilization hardware + wrapping/packaging + indicators + washer-disinfectors + trolleys + tracking is expensive, and it expands with every OT/ICU/NICU upgrade.
Estimated market size (Jan 2026 run-rate): ~USD 50M–80M/year equivalent
Also supported indirectly by the fact that sterilization/sterilizer trade flows into Bangladesh are active (autoclaves/sterilizers show regular import entries).
C) Healthcare waste management products (segregation + collection + treatment + PPE + tracking)
Now here’s the twist: healthcare waste sits inside two bigger markets:
- the health system, and
- The waste management industry.
A market report source projects Bangladesh’s overall waste management market to reach ~USD 3.7B by 2026.
Healthcare waste is a slice of that—smaller than municipal waste, but high-risk and equipment-heavy.
Estimated healthcare waste management product/services slice: ~2%–5% of the overall waste management market
Estimated value: ~USD 75M–185M/year equivalent (planning range)
This aligns with the documented scale and urgency: medical waste governance is repeatedly flagged as a weak point, and waste volumes keep rising.
Bottom line for January 2026 planning:
Rehab + Physio products: ~USD 70M–110M
CSSD sterilization ecosystem: ~USD 50M–80M
Healthcare waste management ecosystem: ~USD 75M–185M
These are ranges built from the best available anchors, not made-up exact figures.
3) Product map: What exactly sells in these categories?
A) Rehabilitation & physiotherapy products (January 2026 Bangladesh demand basket)
1) Clinical physiotherapy equipment (facility-based)
- Electrotherapy units (TENS/IFT)
- Ultrasound therapy devices
- Traction units (cervical/lumbar)
- CPM machines (post-orthopedic surgery recovery)
- Shockwave therapy (higher-end private clinics)
- Laser therapy (select segment)
- Exercise therapy systems (pulley, parallel bar, balance boards)
- Hydrotherapy (limited, premium)
2) Orthotics, supports, and pain management aids (fast-moving)
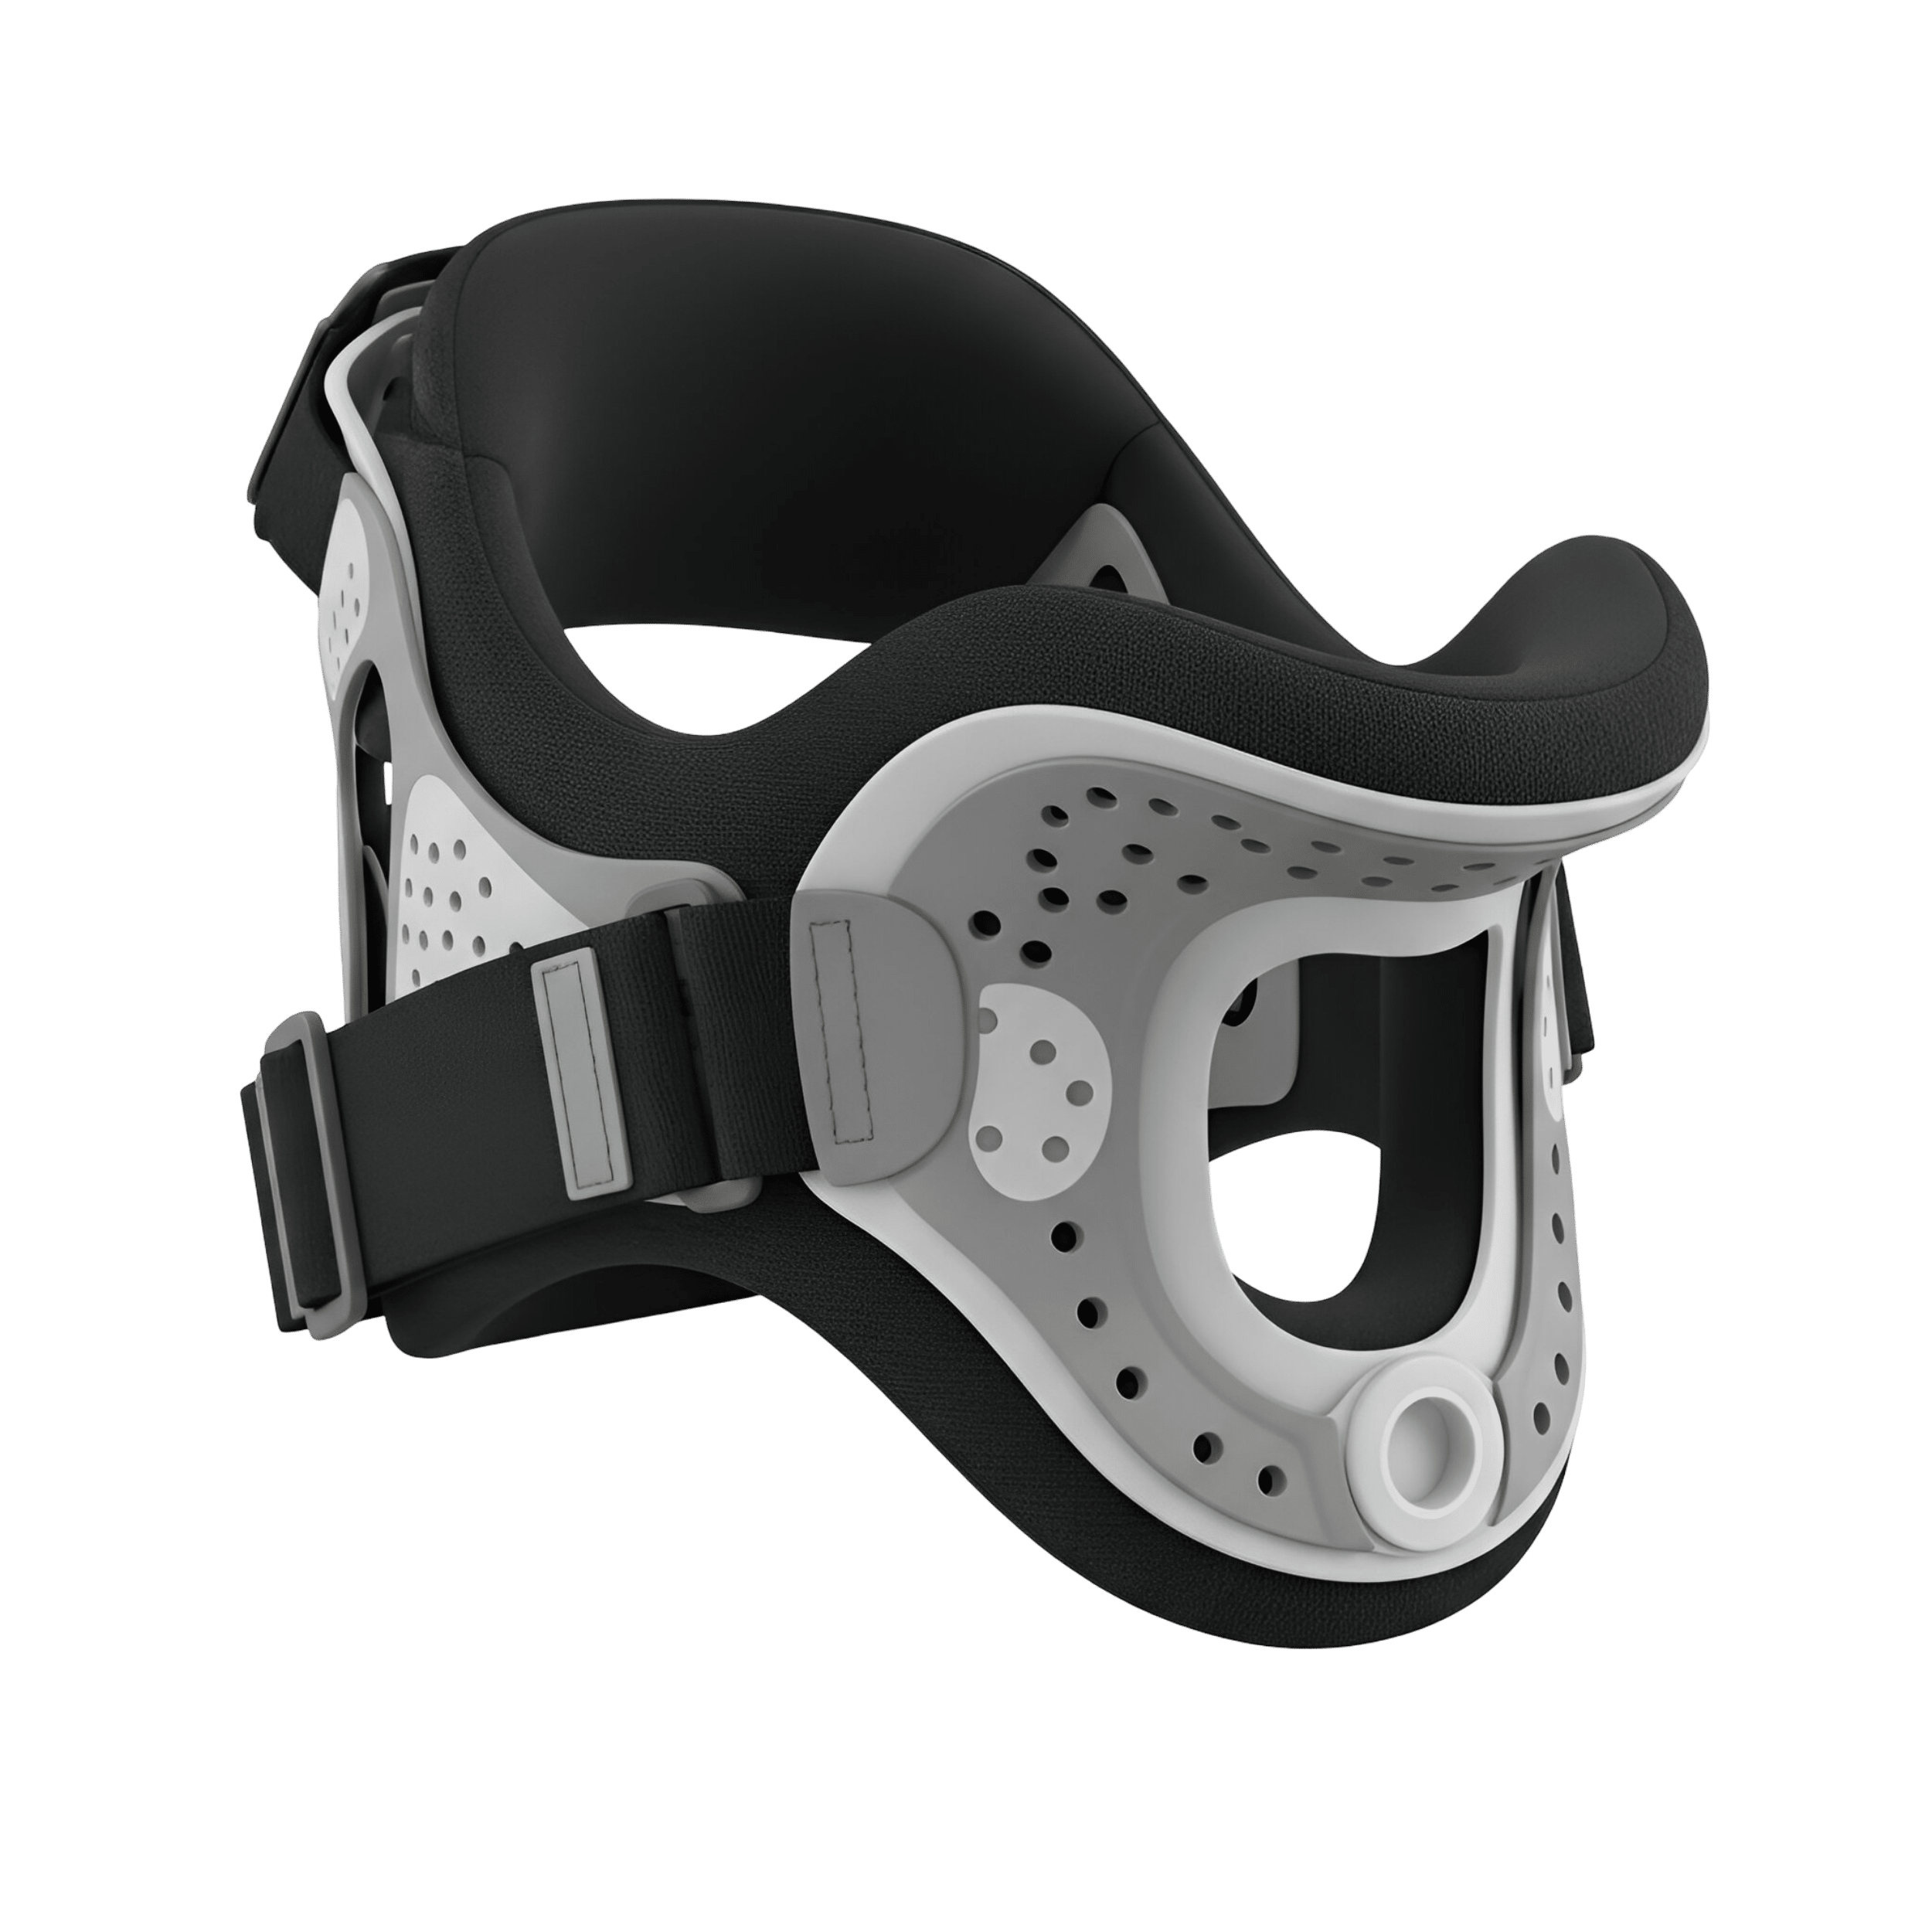
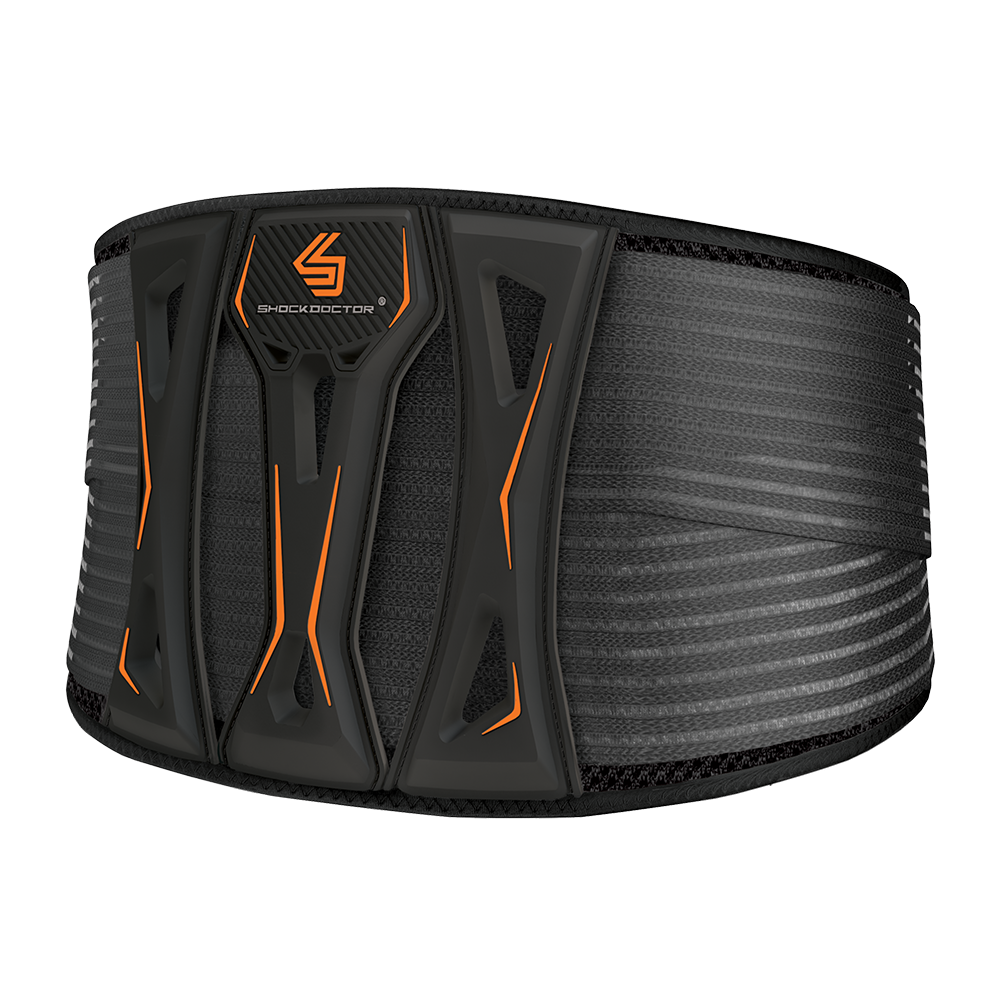
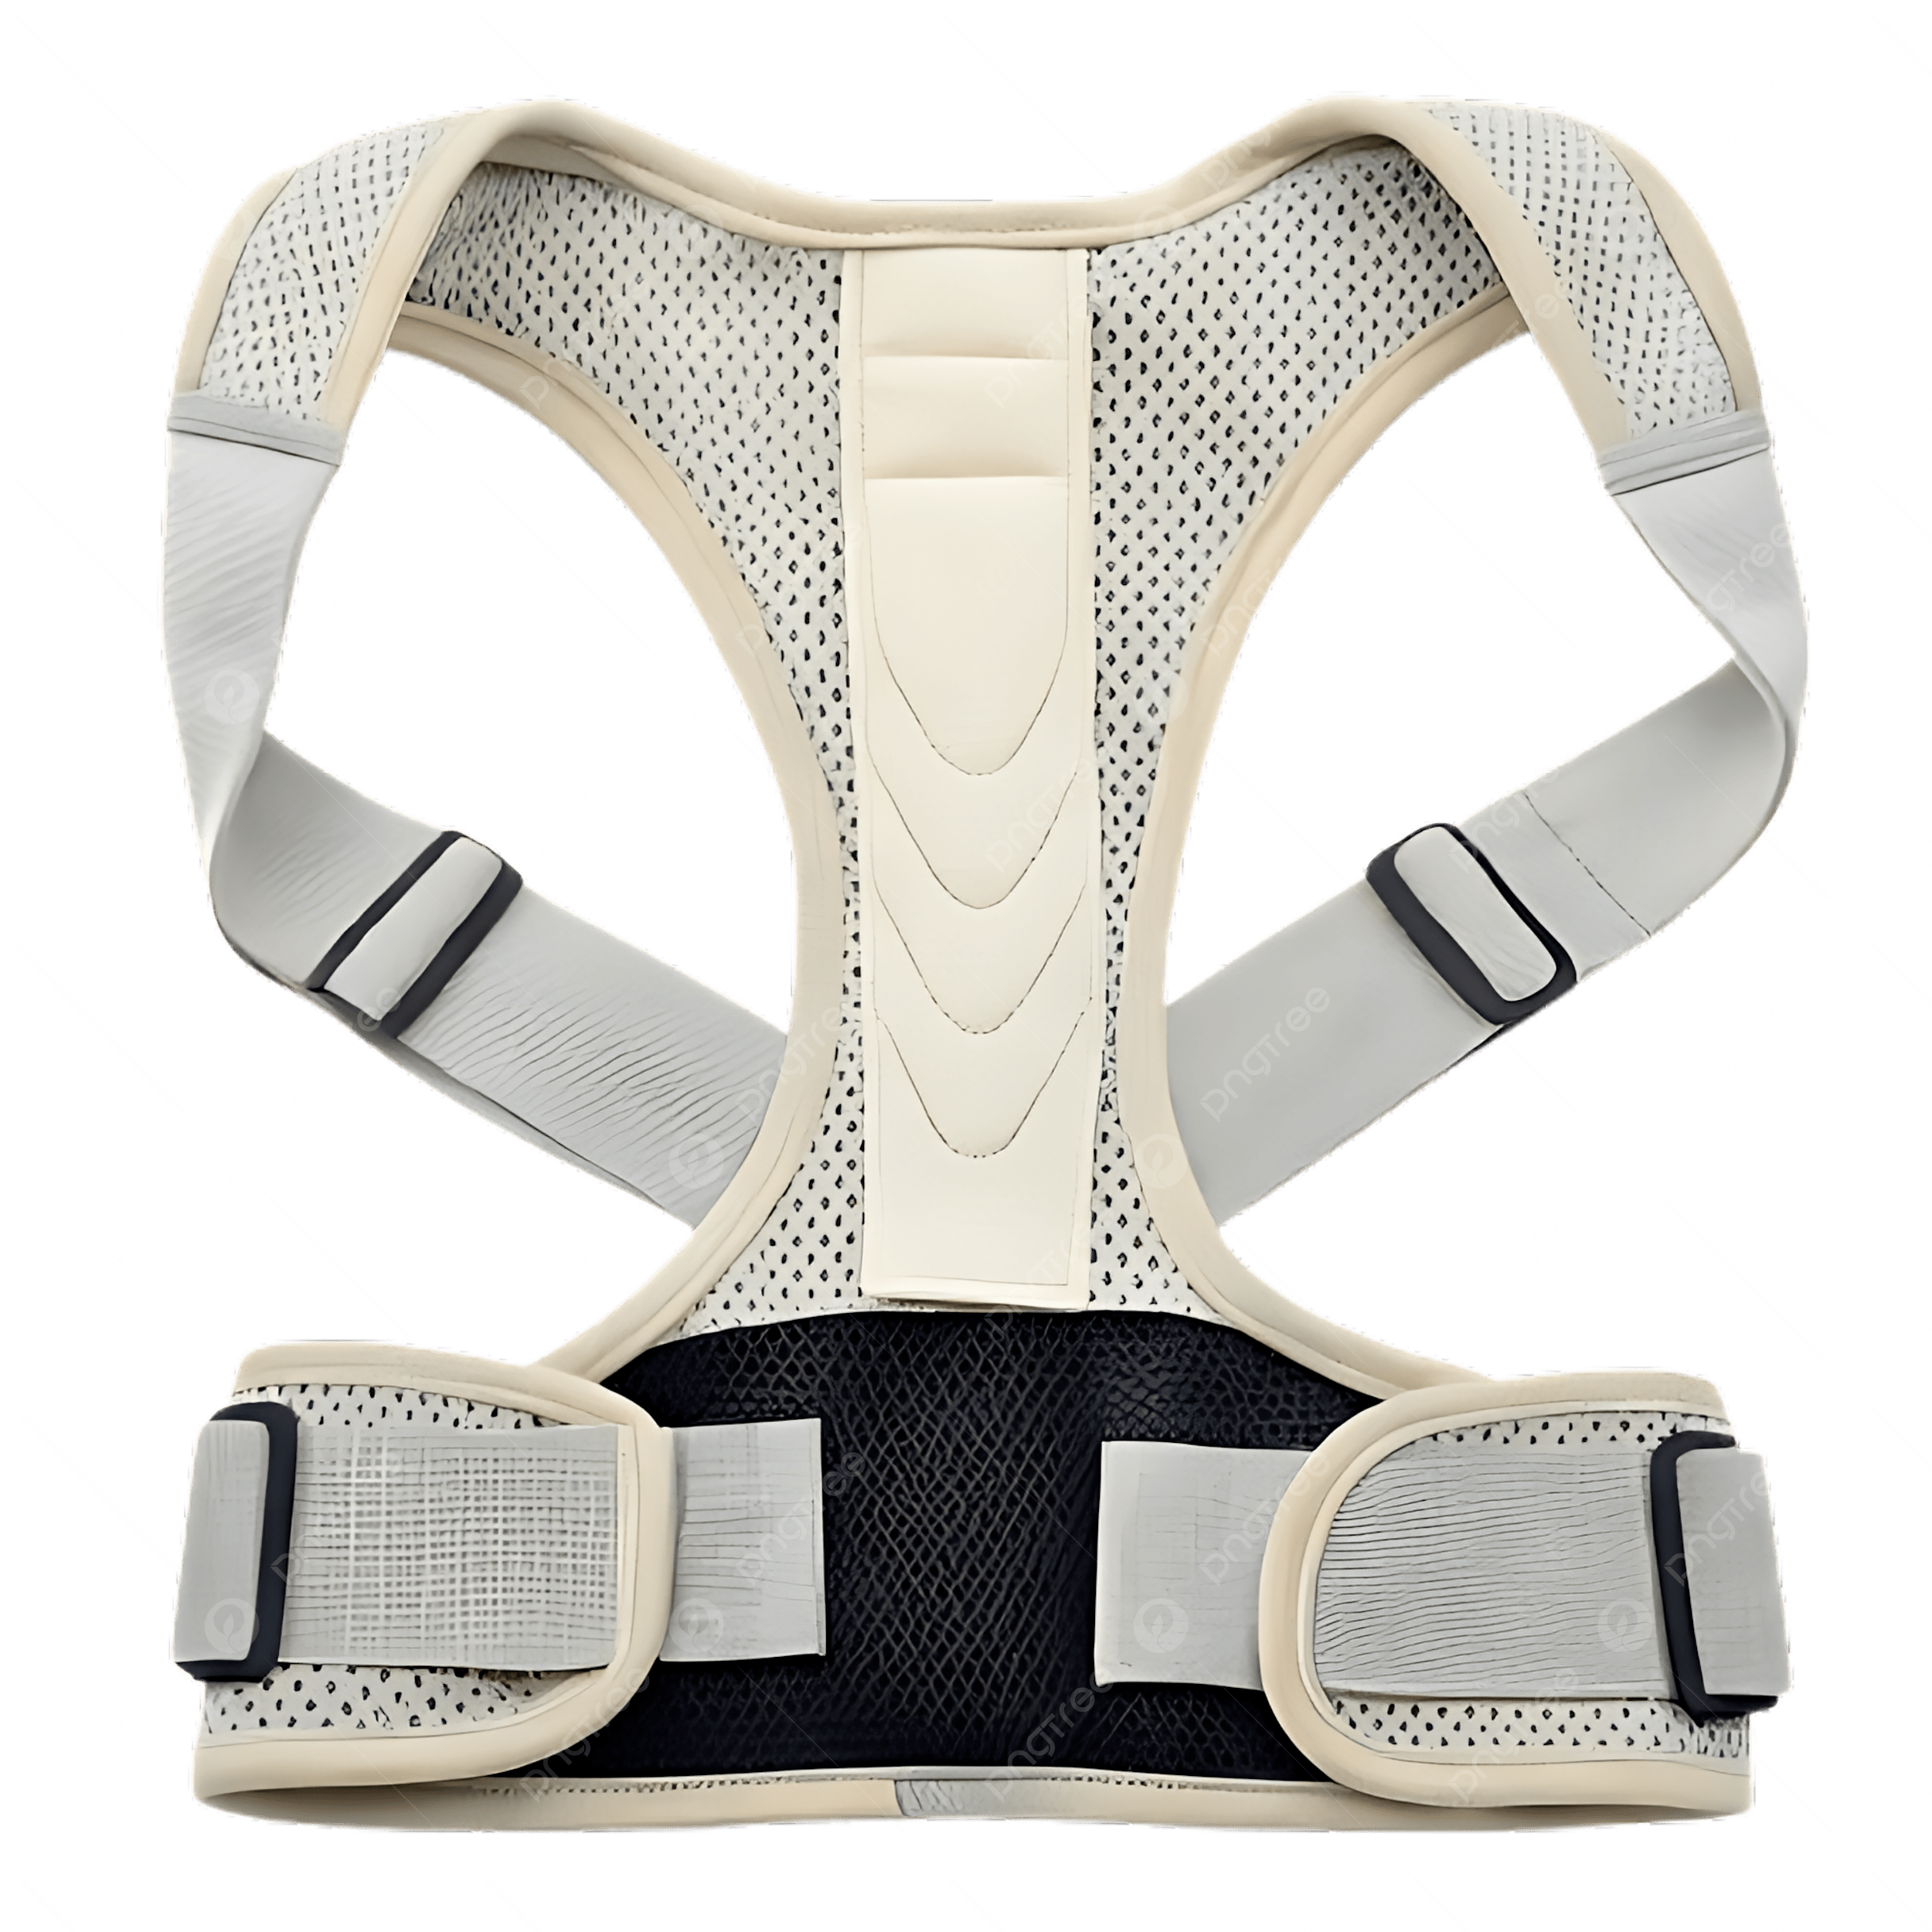
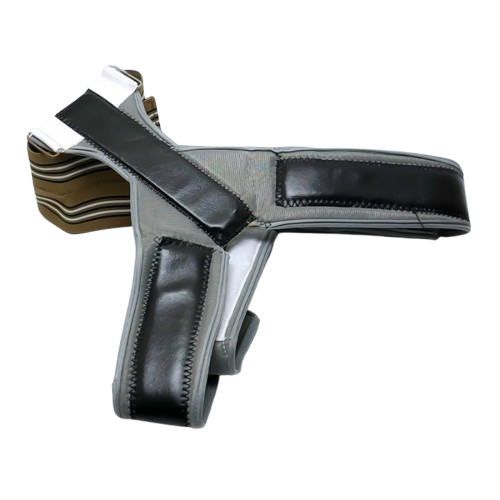
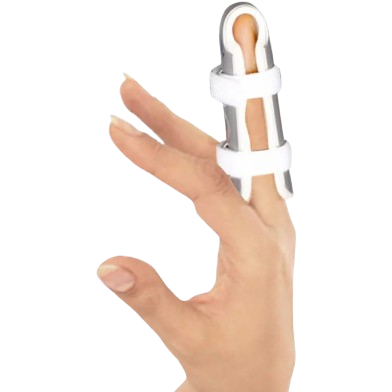
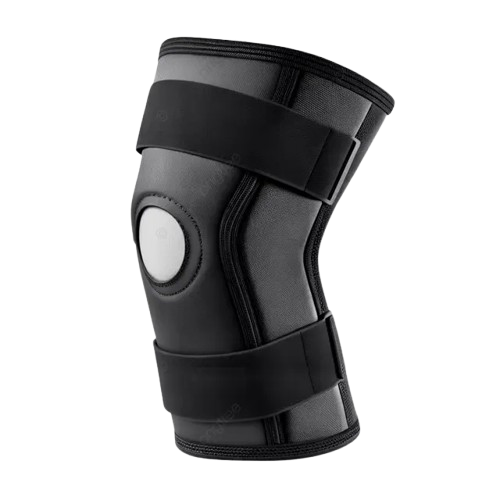
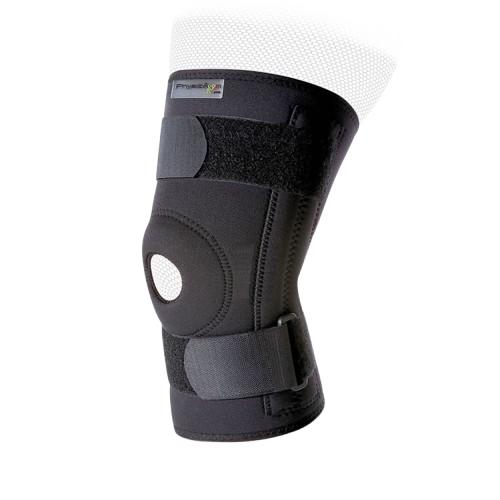
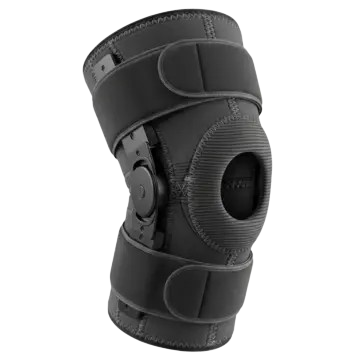
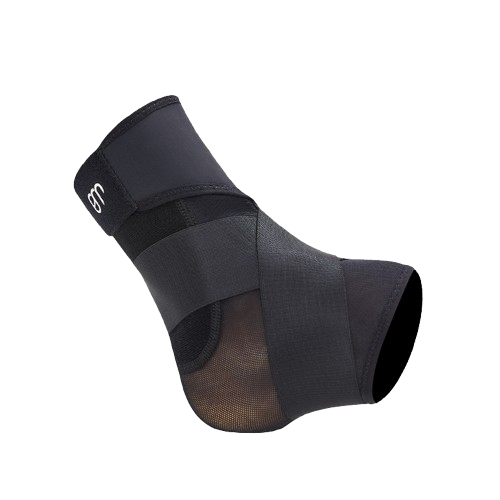
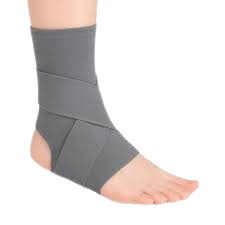
- Cervical collars, lumbar supports, and knee braces
- Abdominal supports and waist trimmers
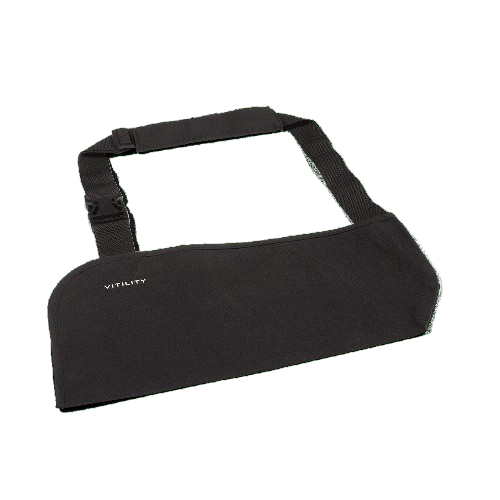
- Arm slings, finger cots, casting tapes
This segment grows because it’s lower-ticket + easy to distribute through pharmacies and online channels.
3) Mobility + home rehab products (growing hard)
- Walkers, crutches, canes
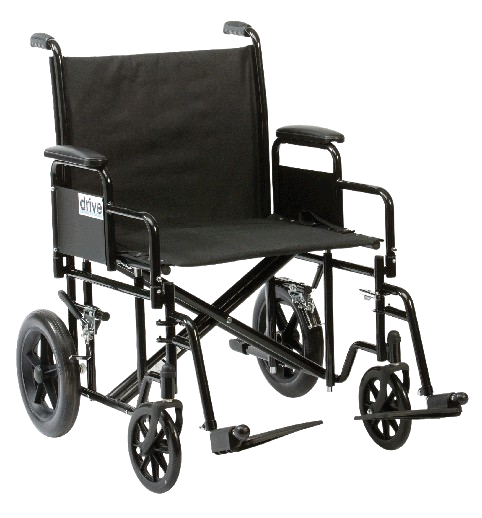
- Wheelchairs (manual + basic powered)
- Patient lifting aids (basic segment)
- Home exercise kits
- Hot/cold therapy products, heating pads
4) Consumables & accessories
- Electrodes, gels, tapes, straps
- Replacement parts, batteries, cuffs
Why it’s growing: Bangladesh is still underserved in rehab workforce density and facility coverage, so home care and pharmacy-driven rehab tools are filling gaps.
B) CSSD products (sterilization + sterile supply chain)
CSSD is not “a room with an autoclave.” It’s a controlled production line: dirty → clean → sterile → distributed.
Core product groups:
- Steam sterilizers/autoclaves (small + large)
- Low-temperature sterilizers (where appropriate)
- Washer-disinfectors / cleaning + decontamination systems
- Ultrasonic cleaners
- Sterile packaging: wraps, pouches, reels
- Indicators + validation: chemical indicators, biological indicators
- Storage + transport: racks, trolleys, case carts
- Tracking & traceability tools (emerging in premium hospitals)
Bangladesh hospital CSSD units increasingly position themselves as infection-control centers (some private hospitals explicitly highlight advanced CSSD operations as a quality differentiator).
C) Healthcare waste management products (segregation → treatment → disposal)
The full product chain:
- Segregation at source: color-coded bins, liners, sharps containers
- Collection: covered trolleys, carts, and PPE sets for handlers
- Storage: secure waste rooms, labeled zones
- Treatment: autoclave-based treatment, shredders, needle destroyers, incineration systems, where applicable
- Transport: sealed transfer systems
- Documentation & compliance: logs, audits, training materials
Bangladesh still struggles with consistent implementation; governance and enforcement gaps are widely discussed.
4) Case study 1 (Rehab): Centre for the Rehabilitation of the Paralysed (CRP)
If you want a real-world Bangladesh rehab demand signal, CRP is one of the clearest mirrors.
From CRP’s annual reporting:
- Physiotherapy served 26,221 outpatients (musculoskeletal + neurological) plus 301 inpatients with spinal cord injury in one reporting year.
- CRP also reports broad national reach and high patient volume across its network.
What this tells the market (January 2026):
- Rehab demand is not niche—it’s mass-volume.
- Outpatient-heavy models dominate, which increases demand for:
- affordable therapy tools
- fast-moving supports
- home rehab products
- Rehab is not only “physio machines”—it’s a whole system of aids, consumables, and continuity tools.
5) Case study 2 (Waste management): Two tertiary hospitals in Dhaka
A Bangladesh-based assessment compared waste management practice in:
- Shaheed Suhrawardy Medical College & Hospital (public)
- Bangladesh Medical College and Hospital (private)
Key findings include:
- Waste generation reported (kg/day): public facility general 1500, infectious non-sharp 110, sharps 13; private facility general 600, infectious 53, sharps 7.
- Waste generation per patient: 1.09 kg/day vs 1.48 kg/day.
- Training gaps are real: training on hospital waste management was reported by 69.8% (public) vs 29.5%(private) respondents.
What this means for the product market:
- Hospitals need not only bins and bags; they need training systems + monitoring + steady supplies.
- Private vs public differences show why “policy exists” doesn’t mean “implementation works.”
- The market is not just procurement—it’s compliance operations.
6) Challenges in January 2026: what’s blocking growth?
A) Rehab & physiotherapy product challenges
- Workforce mismatch
Bangladesh has limited physiotherapy density relative to population; even the professional association’s own published stats show how tight the supply is. - Out-of-pocket dependence
Rehab is often paid directly by patients; that caps uptake for higher-end devices and longer therapy cycles. - Quality variation + grey imports
Markets with high price sensitivity attract low-quality products. This becomes a patient safety and reputation problem. - Weak referral pathways
Doctors may under-refer to rehab, or refer late. That reduces utilization of proper rehab tools.
B) CSSD challenges
- Capex-heavy setup
Sterilizers, washer-disinfectors, validation systems—these require long planning cycles and maintenance budgets. - Process discipline
CSSD is a workflow factory. If hospitals treat it like a storage room, infection control collapses. - Maintenance + calibration gaps
Uncalibrated sterilization equipment is basically theatre. It looks nice, does nothing.
C) Healthcare waste management challenges
- Implementation gaps in segregation, records, and training
Documented directly in local hospital assessments. - Governance and accountability
Governance challenges are flagged in Bangladesh-focused reporting on medical waste systems and policy enforcement. - Urban waste pressure
General waste volumes are huge and rising; city waste systems are stretched, making safe medical waste handling harder to guarantee.
7) Distribution reality in Bangladesh: who buys what?
Rehab/physio products
- Public hospitals: limited budgets, slower procurement
- Private hospitals: higher-end equipment + service contracts
- Clinics/diagnostic centers: fast turnover equipment (electrotherapy, ultrasound therapy)
- Pharmacies & online: supports, braces, home rehab aids (fast-moving)
CSSD products
- Medical colleges + tertiary hospitals: bulk equipment
- New private hospitals: turnkey CSSD setups
- Procurement is often tied to OT expansion projects, accreditation readiness, and infection control.
Waste management products
- Hospitals (public/private)
- City-linked waste vendors
- Specialized service providers (where present)
- Procurement is increasingly linked to compliance audits and reputational risk.
8) What government + regulators should prioritize (2026-ready moves)
Not the fluffy kind. The practical kind.
- Standardize minimum CSSD requirements for facility categories (district → tertiary → specialized).
- Mandatory training + certification loops for waste handlers, CSSD staff, and ward-level waste segregation leads.
- Enforced reporting: waste logs, treatment method, audit schedules (digital reporting where feasible).
- Procurement standards: minimum quality specs for sterilizers, indicators, sharps systems, and waste containment.
- Local manufacturing encouragement for:
- bins, liners, sharps containers
- Basic rehab supports and braces
- hospital trolleys and CSSD transport items
This reduces dependency and improves availability.
9) January 2026 outlook: where the market is going next
Rehab & physiotherapy
- Growth will continue as long as NCD + aging + surgery volumes rise.
- Biggest growth lanes:
- home rehab products
- affordable clinic equipment
- orthopedic supports + consumables
CSSD
- Demand rises with every OT/ICU/NICU upgrade and every push for better infection control.
- Expect “traceability” (tracking packs/instruments) to become more common in premium hospitals.
Healthcare waste management
- Growth is forced by reality: rising volumes + rising scrutiny.
- The market will shift from “bins and bags” to systems: treatment, tracking, training, audits, and service contracts.
Plastic Furniture & Velvet Furniture in Bangladesh: From Classrooms to Contemporary Living (January 2026 Perspective)
Furniture tells the quiet story of a nation. What we sit on, study on, relax on—it reflects economics, climate, lifestyle, and aspiration. In Bangladesh, two furniture categories sit at opposite ends of the material spectrum yet grow side by side with equal relevance: plastic furniture (including school furniture) and velvet furniture.
One is practical, resilient, and democratic.
The other is expressive, aspirational, and emotional.
In January 2026, both are booming—driven by population growth, urbanization, education expansion, and a rising middle class that wants comfort and character. Let’s unpack the market, the products, the challenges, and where this story is headed.
1. Plastic Furniture in Bangladesh: The Backbone of Everyday Living
Plastic furniture is not a compromise anymore—it’s a design and durability decision. In Bangladesh’s climate, where humidity, dust, and heavy use are daily realities, plastic furniture has evolved from “cheap seating” to essential infrastructure.
Why plastic furniture dominates
- Weather-resistant (humidity, monsoon, heat)
- Lightweight and portable
- Low maintenance
- Affordable for mass use
- Increasingly aesthetic with modern molds and finishes
From tea stalls to conference rooms, plastic furniture is everywhere—and it’s not going anywhere.
2. Plastic School Furniture: Educating a Nation, One Chair at a Time
School furniture deserves its own spotlight. Bangladesh’s education sector—public schools, madrasas, private schools, coaching centers, NGOs, vocational institutes—is massive. Every classroom needs desks, benches, chairs, and tables, and they need to survive years of intense use.
Why plastic is winning in schools
- Cost efficiency: Lower upfront cost than wood or steel-wood hybrids
- Uniformity: Easy to standardize across thousands of institutions
- Durability: Resistant to termites, moisture, chalk dust
- Mobility: Easy to rearrange classrooms
- Hygiene: Easier to clean and sanitize
Common plastic school furniture products
- Student chairs (with/without writing pads)
- Student desks (single and shared)
- Teacher chairs and tables
- Exam benches
- Training-room chairs
- Kindergarten furniture (colorful, child-safe)
By January 2026, plastic school furniture will no longer viewed as “temporary.” It’s considered institution-grade, especially when reinforced designs and thicker polymer blends are used.
3. Market Size & Growth: Plastic Furniture (Including School Segment)
Market reality (January 2026 estimates)
- Plastic furniture represents 30–40% of Bangladesh’s total furniture volume (unit-wise).
- School and institutional plastic furniture contributes 20–25% of plastic furniture demand.
- Annual growth rate: 8–12%, driven by:
- New schools and colleges
- Classroom expansion
- NGO and donor-funded education projects
- Urban coaching centers and training institutes
Plastic furniture is a volume game—high units, moderate margins, fast turnover.
4. Design Evolution: Plastic Furniture Isn’t Ugly Anymore
Let’s be honest—plastic furniture used to look… tragic. Today? Different story.
What changed
- Better injection molding technology
- Ergonomic designs
- Matte and textured finishes
- Neutral and pastel color palettes
- Hybrid designs (plastic + metal legs)
Schools now care about posture, adults care about aesthetics, and plastic furniture manufacturers have finally listened.
5. Challenges in the Plastic & School Furniture Segment
No sugar-coating—this segment has issues.
Key challenges
- Quality inconsistency
Thin plastic, recycled-content overload, and weak load-bearing designs damage trust. - Price wars
Many players compete only on price, racing to the bottom. - Environmental pressure
Plastic sustainability is under scrutiny. Buyers increasingly ask:- Is it recyclable?
- Is it durable enough to justify plastic use?
- Procurement delays in the public sector
School furniture projects often face tender delays and budget cycles.
Despite this, demand keeps growing—because alternatives are either more expensive or less climate-friendly.
6. Velvet Furniture: Where Comfort Meets Character
Now let’s cross the room—from classrooms to living rooms.
Velvet furniture represents aspiration. It’s about texture, warmth, and emotional comfort. In Bangladesh, velvet has made a powerful comeback, especially among:
- Urban middle and upper-middle-class families
- Boutique hotels and serviced apartments
- Offices, lounges, and studios
- Event and hospitality spaces
Velvet says: we’ve arrived.
7. Why Velvet Furniture Is Trending in Bangladesh
Velvet works beautifully with:
- Warm lighting
- Compact urban homes
- Contemporary and classic interior styles
Drivers behind the velvet boom
- Rising apartment culture
- Growth of interior design services
- Social media-driven aesthetics
- Desire for hotel-like comfort at home
By January 2026, velvet furniture will no longer be “elite-only.” It’s aspirational but accessible.
8. Popular Velvet Furniture Products
Residential
- Velvet sofas (2-seater, 3-seater, L-shape)
- Accent chairs
- Ottoman stools
- Bed headboards
- Dining chairs (velvet upholstered)
Commercial
- Lounge seating
- Office reception sofas
- Hotel lobby furniture
- Boutique café seating
Velvet is often paired with:
- Wooden frames
- Metal accents (gold, black, brass)
- Neutral or jewel tones (emerald, navy, maroon, beige)
9. Market Size & Growth: Velvet Furniture
January 2026 snapshot
- Velvet furniture is a smaller but high-value segment.
- Estimated share of upholstered furniture market: 15–20%.
- Growth rate: 12–15% annually, faster than general furniture.
Why faster growth? Because velvet rides on lifestyle aspiration, not just necessity.
10. Velvet Furniture Challenges (Yes, There Are Some)
Velvet looks luxurious—but it demands discipline.
Key challenges
- Maintenance concerns
Dust, pet hair, and stains worry buyers (even though modern velvet is more forgiving). - Climate misconceptions
Many still believe velvet is “too hot” for Bangladesh—education is needed. - Quality variation
Low-grade velvet pills and fades fast, hurting consumer confidence. - Skilled upholstery shortage
Good velvet furniture needs skilled labor—still limited in some regions.
Yet despite these, velvet keeps winning hearts because nothing else feels quite the same.
11. Plastic vs Velvet: Not a Competition, a Balance
Here’s the truth: plastic and velvet furniture don’t compete—they complete the market.
| Plastic Furniture | Velvet Furniture |
| Functional | Emotional |
| Mass-market | Lifestyle-driven |
| Schools & institutions | Homes & hospitality |
| Weather-resistant | Comfort-focused |
| Volume-led | Value-led |
Bangladesh needs both:
- Plastic to educate, equip, and operate
- Velvet to express, relax, and elevate
12. Sustainability & the Road Ahead
Plastic furniture future
- Shift toward recyclable polymers
- Thicker, longer-life designs
- Institutional standards for schools
- Repair and reuse mindset
Velvet furniture future
- Performance velvet (easy-clean, stain-resistant)
- Locally sourced frames
- Modular designs for apartments
- Custom colors and textures
Furniture in Bangladesh is moving from “just use” to use with intention.
13. January 2026 Outlook: What to Expect Next
- Plastic school furniture demand will continue rising with education expansion.
- Velvet furniture will grow alongside the interior design and real estate sectors.
- Hybrid spaces (schools with aesthetic seating, offices with velvet lounges) will blur boundaries.
- Buyers will demand value + durability + design—no longer one without the other.
Final Thought
Furniture is silent—but it shapes daily life.
Plastic furniture holds classrooms together, supports learning, and survives chaos with grace.
Velvet furniture softens homes, adds dignity to spaces, and reminds us that comfort matters.
In Bangladesh, January 2026 isn’t about choosing one over the other.
It’s about building spaces that work—and spaces that feel like home.

Related Posts
Uncategorized
How FH Plastics Ensures Durable, Safe Products
How FH Plastics Ensures Durable, Safe Products Durability and safety are…
Uncategorized
5 Ways Plastic Manufacturing Is Going Green in 2026
For years, “green plastics” was mostly a marketing line. In 2026…
Uncategorized
Recyclable vs Non-Recyclable Plastics: What Manufacturers Need to Know
Not all plastic is created equal. Two containers that look identical…
Uncategorized
The Future of Plastics Manufacturing in South Asia
South Asia has spent two decades building plastics manufacturing capacity. The…