The Future of Plastics Manufacturing in South Asia

South Asia has spent two decades building plastics manufacturing capacity. The next decade will be about what that capacity gets used for.
The region’s factories have grown around a straightforward proposition: competitive labour, growing domestic demand, and proximity to major consumption markets. That proposition is still valid, but the conditions around it are changing — in feedstock supply, in buyer requirements, in environmental regulation, and in the kind of products that command a margin.
Here is where the sector appears to be heading.
The Current Position
The region’s plastics sector has genuine scale. India hosts a large, integrated industry with domestic petrochemical capacity supporting downstream converters. Bangladesh operates more than 6,000 plastic manufacturing units employing around 1.5 million workers, serving a domestic market valued near USD 3 billion and growing roughly 20% annually, with export growth reaching about 21% in FY25. Pakistan and Sri Lanka maintain substantial converting bases serving domestic demand and regional trade.
Per-capita plastic consumption across South Asia remains well below global averages, which is the sector’s core growth argument. Rising incomes, urbanisation, packaged food consumption, healthcare expansion, and infrastructure investment all point the same direction — more demand, sustained over a long period.
Five Forces That Will Shape the Next Decade
1. Feedstock: The Structural Divide
The most consequential difference within the region is upstream integration. Countries with domestic petrochemical capacity control their input costs to a degree that importers cannot.
Bangladesh imports nearly all its polymer feedstock, leaving manufacturers exposed to international price movements, currency pressure, freight disruption, and port delays. Regional supply chain shocks have repeatedly forced production cuts and pushed up costs across the sector.
Two responses are available. One is upstream investment, which is capital-intensive and slow. The other — more accessible for most manufacturers — is building domestic recycled feedstock capacity. Recycled resin produced locally is insulated from import volatility and addresses waste management simultaneously. This is likely to be the more consequential path for the smaller economies in the region.
2. Buyer Requirements Are Rewriting the Qualification Bar
Export buyers now audit far beyond price and lead time. Recycled content percentages, restricted substance compliance, environmental management certification, social compliance, and traceability documentation are becoming entry requirements rather than differentiators.
This creates a widening gap. Factories that build compliance capability access buyers that others cannot reach — and those buyers tend to place larger, more stable, longer-term orders. Factories competing on price alone find themselves in the most crowded and least profitable part of the market.
For the region’s largely SME-based sector, this is the central strategic question of the next five years: invest in capability, or compete indefinitely on cost.
3. Regulation Arrives, Unevenly
Single-use plastic restrictions, extended producer responsibility schemes, and waste management rules are being introduced across South Asian markets at varying speeds and with varying enforcement.
The direction is unambiguous even where implementation lags. Manufacturers who anticipate EPR obligations, design for recyclability, and build recycled content capability will adapt at manageable cost. Those who wait will face compressed timelines.
Export markets add another layer. Even where domestic regulation is light, European and North American packaging rules reach back through the supply chain to the manufacturer.
4. Supply Chain Diversification Creates Opening
Global buyers continue to spread manufacturing risk across multiple countries rather than concentrating it. This has directed attention toward South Asian suppliers for plastic components, packaging, and accessories.
The opportunity is real but conditional. Winning that work requires the capability described above — documented quality systems, compliance evidence, consistent delivery, and the technical capacity to make what the buyer specifies rather than what the factory currently produces.
5. Technology Adoption Accelerates Under Cost Pressure
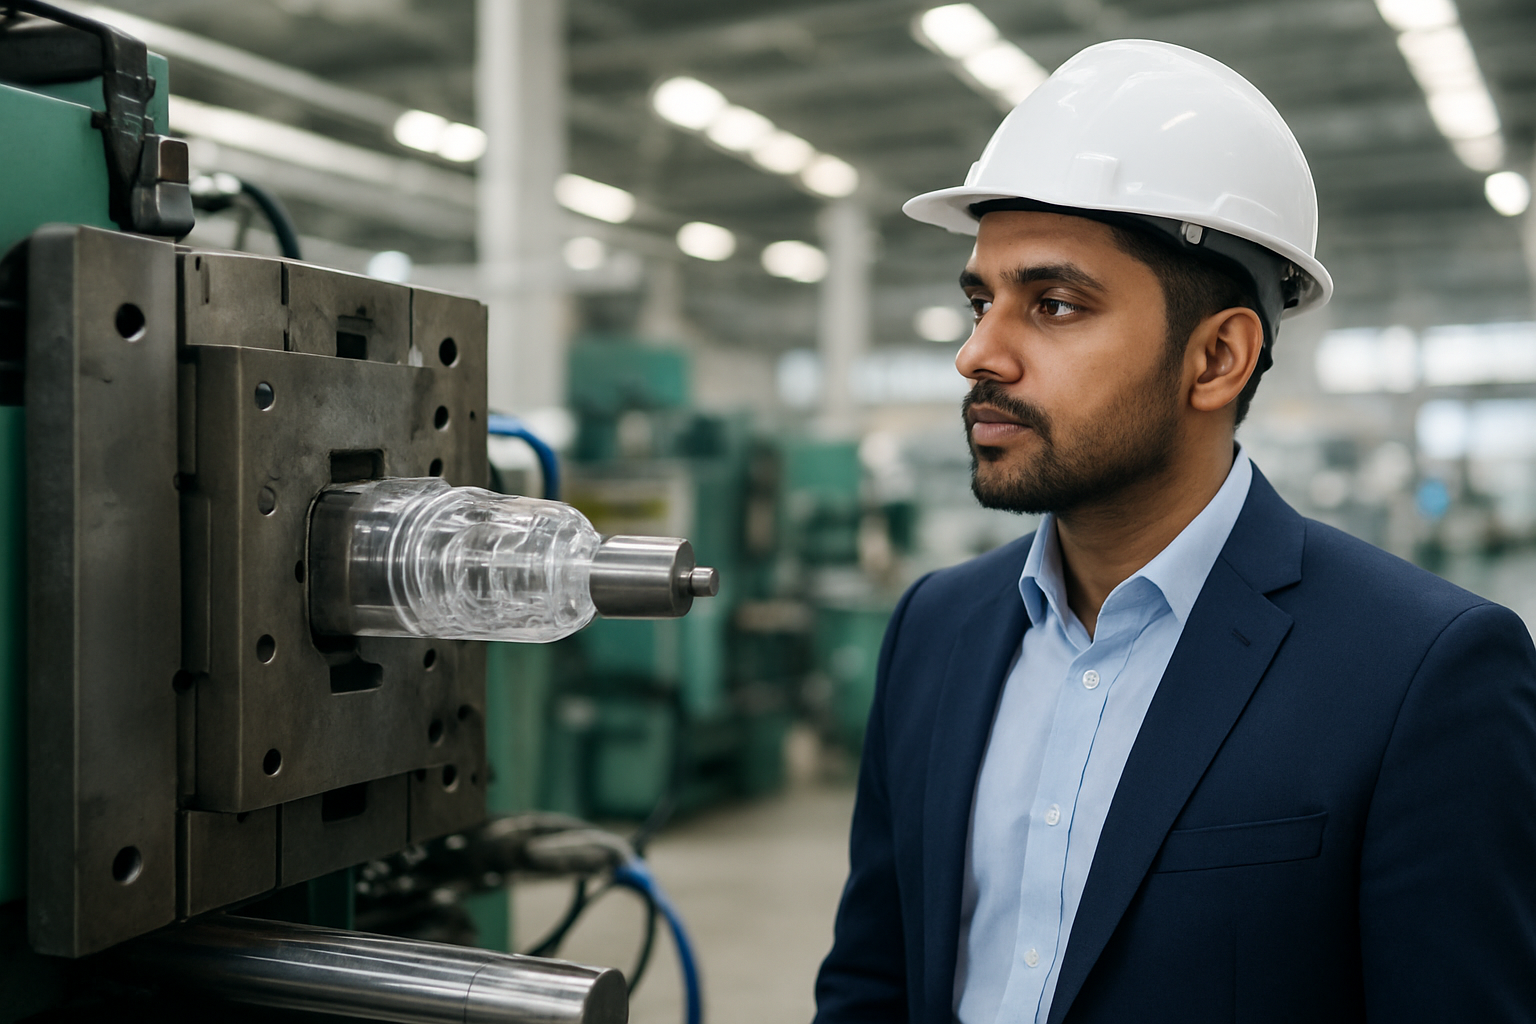
Energy costs and quality demands are driving equipment modernisation. Servo-hydraulic and all-electric moulding machines, automated take-out and inspection, cavity pressure monitoring, and simulation-driven tool design are moving from the largest factories toward the mid-tier.
Foreign machinery suppliers report growing demand from the region for injection moulding equipment, PP woven bag lines, PET blow moulding machines, and printing units — a reliable indicator of where investment is going.
The Value Chain Question
The strategic choice facing the region’s manufacturers can be stated simply.
Commodity path: high-volume household goods, basic packaging, standard films. Competition is on price, margins are thin, and the position is vulnerable to any competitor with lower costs or better scale.
Value path: engineering components, medical-grade products, technical packaging, automotive and electrical parts, precision moulding. Requires tooling capability, process control, material expertise, and compliance systems. Competition is on capability, and customer relationships are durable because switching costs are real.
The value path is harder and slower. It is also the only route to margins that survive the next competitor.
Circularity as Competitive Infrastructure
Waste management is frequently framed as an environmental obligation. For South Asia it is better understood as a supply opportunity.
The region generates enormous volumes of post-consumer plastic. Currently much of it is either unrecovered or handled through informal collection with limited processing capability. Formalising collection, investing in washing and granulation capacity, and producing verified-quality recycled resin would simultaneously reduce import dependence, create employment, address the visible waste problem that shapes public opinion about the industry, and meet the recycled content requirements that buyers increasingly specify.
Few industrial opportunities align environmental and commercial interests this directly.
What Success Looks Like by 2035
A realistic strong outcome for the region’s plastics sector would include:
- A meaningful share of feedstock supplied by domestic recycling rather than imports
- A cluster of manufacturers certified and equipped for medical, food-grade, and technical component production
- Export composition shifted toward higher-value categories rather than commodity goods
- Functioning collection and processing infrastructure with formal employment
- A skilled technical workforce in mould design, process engineering, and quality management
- Energy-efficient installed capacity replacing ageing hydraulic equipment
None of this happens automatically. Each element requires deliberate investment by manufacturers and coherent support from policy.
The Factory-Level View
For a manufacturer, national trends resolve into concrete decisions: which certifications to pursue, which machines to replace, which customers to target, which capabilities to build before they are demanded. FH Plastics Industry approaches the coming decade with the same principle that governs its production floor — capability built deliberately outlasts capacity added opportunistically.
Conclusion
The future of plastics manufacturing in South Asia is not in doubt in terms of volume. Demand growth is structural. What remains open is whether the region’s manufacturers move up the value chain or stay locked in commodity competition, and whether circular material systems get built before regulation makes them mandatory.
The factories making those choices now are the ones that will define the sector a decade from now.

Related Posts
Uncategorized
How FH Plastics Ensures Durable, Safe Products
How FH Plastics Ensures Durable, Safe Products Durability and safety are…
Uncategorized
5 Ways Plastic Manufacturing Is Going Green in 2026
For years, “green plastics” was mostly a marketing line. In 2026…
Uncategorized
Recyclable vs Non-Recyclable Plastics: What Manufacturers Need to Know
Not all plastic is created equal. Two containers that look identical…
Uncategorized
The Future of Plastics Manufacturing in South Asia
South Asia has spent two decades building plastics manufacturing capacity. The…